Consumer finance covers many of the financial products people use to pay for purchases, manage short-term cash needs or spread the cost of larger expenses.
That can include credit cards, personal loans, overdrafts, car finance, retail finance and Buy Now, Pay Later (BNPL).
The important point is that borrowing is not automatically good or bad. What matters is whether the product is suitable for your circumstances, how much it costs and whether you can comfortably manage the repayments.
This guide explains consumer finance in the UK, the main types of borrowing available, what to compare before applying and the risks you should understand.
Key Takeaways
- Consumer finance includes a wide range of ways to borrow or spread payments.
- Credit cards, loans, overdrafts and vehicle finance work differently and have different costs.
- The cheapest-looking monthly payment is not necessarily the cheapest option overall.
- APR, interest, fees and the total amount repayable are important when comparing credit.
- Lenders generally assess your creditworthiness and affordability before approving regulated credit.
- If borrowing would make it difficult to pay essential household bills, getting free debt guidance may be more appropriate than taking on more credit.
What Is Consumer Finance?
Consumer finance is a broad term for financial products and services that help individuals pay for goods and services, borrow money or manage their personal finances.
In everyday use, the term is often associated with consumer credit — borrowing that allows a person to receive something now and repay the money over time, usually with interest or other charges.
Common examples include:
- Credit cards
- Personal loans
- Overdrafts
- Car finance
- Retail finance
- Buy Now, Pay Later
- Some other forms of consumer borrowing
The FCA describes consumer credit as covering products including credit cards, personal loans, retail and motor finance, overdrafts and BNPL, as well as related services such as credit broking and debt advice.
Consumer finance is therefore broader than simply taking out a personal loan. The right option depends on why you need the money, how much you need and how quickly you can repay it.
How Does Consumer Finance Work?
The basic principle is straightforward.
A lender or finance provider gives you access to money or allows you to pay for something without paying the entire cost immediately. You then repay the amount according to agreed terms.
Depending on the product, you may pay:
- Interest
- A fixed or variable rate
- Arrangement or transfer fees
- Late-payment charges
- Other applicable charges
For example, a personal loan might provide a lump sum that you repay in fixed monthly instalments over an agreed period.
A credit card works differently. You normally have a credit limit and can borrow repeatedly up to that limit, subject to the account terms and your ability to make the required repayments.
An overdraft allows you to spend more than the balance available in your current account, up to an agreed limit.
The cost and risks can therefore vary considerably between products.
7 Common Types of Consumer Finance
1. Credit Cards
A credit card gives you access to a revolving credit facility.
You can use it to make purchases up to your available credit limit and then repay the balance according to the card’s terms.
Some cards offer promotional interest-free periods, while others charge interest on borrowing.
Before choosing a credit card, consider:
- Interest rate and APR
- Annual or other fees
- Credit limit
- Promotional period
- Balance-transfer fees
- Minimum monthly payment
- What happens when a promotional rate ends
Making only minimum payments can take considerably longer to clear a balance and increase the total cost of borrowing. MoneyHelper recommends considering whether you can afford the repayments before applying for credit.
2. Personal Loans
A personal loan usually provides a fixed amount that you repay over an agreed period.
Personal loans are generally unsecured, meaning they are not normally secured against your home or another asset.
They can be useful when you need a known amount of money and want predictable repayments.
However, you should compare:
- APR
- Monthly repayment
- Loan term
- Total amount repayable
- Early repayment conditions
- Late-payment charges
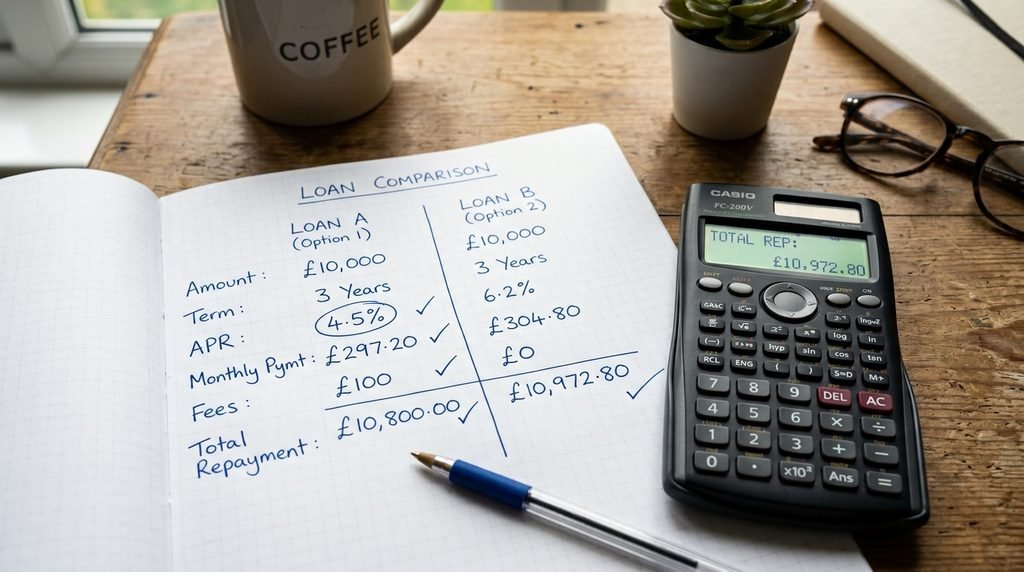
A longer loan term may reduce the monthly payment but can increase the overall interest paid.
3. Overdrafts
An overdraft allows you to spend more than the money currently available in your bank account, subject to your agreed limit and account terms.
It can be useful for short-term cash-flow problems, but it can become expensive if you rely on it continuously.
MoneyHelper notes that overdrafts can involve daily interest, while the FCA has highlighted consumer confusion around overdraft costs and how overdrafts can become persistent borrowing.
If an overdraft is being used every month simply to cover normal living expenses, that may be a sign that your budget needs attention rather than an indication that you need a larger overdraft.
4. Car Finance
Car finance allows consumers to spread the cost of purchasing or using a vehicle.
Different arrangements can have different ownership, deposit, mileage and end-of-agreement conditions.
Before agreeing to vehicle finance, look beyond the monthly payment.
Check:
- Deposit
- Monthly payments
- Agreement length
- Total amount payable
- Mileage restrictions where applicable
- Final or balloon payment where applicable
- Early termination or repayment conditions
- What happens at the end of the agreement
A lower monthly payment does not necessarily mean the agreement is cheaper overall.
5. Buy Now, Pay Later
Buy Now, Pay Later allows consumers to defer or split payments for purchases.
The regulatory position has changed in the UK. From 15 July 2026, the FCA began regulating Deferred Payment Credit (DPC), commonly associated with interest-free BNPL arrangements that meet the relevant definition.
Consumers should still understand the repayment schedule before using BNPL.
Check:
- How many payments are required
- When each payment is due
- Whether interest can apply
- Whether late fees can apply
- What happens if you miss a payment
- Which business is providing the credit
The FCA says regulated DPC lenders need to provide important information about the amount borrowed, repayments, applicable late fees and consumer rights.
6. Retail Finance
Retail finance allows customers to spread the cost of goods or services rather than paying the full price immediately.
It may be offered when purchasing items such as:
- Furniture
- Electronics
- Appliances
- Vehicles
- Other expensive goods
Promotional offers can sometimes make this type of finance attractive, but always read the full terms.
Pay particular attention to what happens after an introductory period and the total amount you will repay.
7. Other Consumer Credit
Consumer finance can also include other forms of borrowing and credit arrangements.
Depending on the circumstances, these may include:
- Money-transfer credit cards
- Balance-transfer cards
- Certain specialist credit products
- Guarantor lending
- Some high-cost credit products
The important principle is the same: understand how much you receive, how much you repay, when you repay it and what happens if you cannot keep up with payments.
Consumer Finance vs Consumer Credit
The two terms are closely related but are not always used in exactly the same way.
Consumer credit generally refers specifically to borrowing and credit arrangements offered to consumers.
Consumer finance is a broader phrase that can describe consumer-focused financial products and services, with consumer credit being an important part of it.
For someone comparing borrowing options, however, the distinction is less important than understanding the actual product and its terms.
If you are considering a loan, credit card or other borrowing product, focus on the cost, affordability, risks and conditions rather than the label used to describe it.
What Does Consumer Finance Cost?
The cost of borrowing depends on the product and your individual circumstances.
Three things deserve particular attention.
Interest Rates
Interest is the cost charged for borrowing money.
A lower interest rate can reduce the cost of borrowing, but it is not the only figure that matters.
Two products can have different fees, terms or repayment structures even when their advertised interest rates appear similar.
APR
APR stands for Annual Percentage Rate.
It is designed to help consumers understand the cost of credit by incorporating interest and certain compulsory charges into an annualised figure.
However, you should still read the product’s full terms rather than relying on one number.
Fees and Charges
Some products can involve additional costs.
Depending on the product, these could include:
- Annual fees
- Arrangement fees
- Balance-transfer fees
- Cash-withdrawal charges
- Late-payment fees
- Early repayment charges
Always check the fee structure before applying.
Why the Total Repayment Matters
One of the easiest mistakes is to focus only on the monthly payment.
Imagine two borrowing options:
| Option A | Option B | |
|---|---|---|
| Amount borrowed | £5,000 | £5,000 |
| Monthly payment | Lower | Higher |
| Repayment period | Longer | Shorter |
| Total cost | Potentially higher | Potentially lower |
The exact outcome depends on the interest rate and fees, but the example illustrates an important principle:
A lower monthly payment does not automatically mean a cheaper financial product.
MoneyHelper recommends comparing the interest rate or APR, total repayment, penalties and monthly or weekly cost when considering borrowing.
How Lenders Decide Whether You Can Afford Credit
When you apply for regulated credit, lenders generally assess your creditworthiness and affordability.
They may consider information such as:
- Income
- Regular expenses
- Existing borrowing
- Credit history
- Existing financial commitments
- Information from credit reference agencies
The FCA says lenders must assess a customer’s creditworthiness, including affordability, before lending and should be reasonably satisfied that the customer can afford repayments without an adverse impact on their overall financial situation.
This is one reason you should provide accurate information when applying.
Don’t exaggerate your income or leave out important financial commitments simply to improve your chances of approval.
How Your Credit Report Can Affect Borrowing
Your credit report contains information about your borrowing history.
It may show:
- Existing credit accounts
- Outstanding balances
- Repayment history
- Applications for credit
- Financial information used by lenders
Before applying for significant borrowing, it can be sensible to check your credit reports for errors.
MoneyHelper recommends checking for mistakes such as an incorrect address or an account that should have been closed.
If you find inaccurate information, contact the relevant credit reference agency and provider.
Avoid Making Multiple Applications Without Checking Eligibility
Repeated applications within a short period can be unhelpful.
Where available, an eligibility checker can give you an indication of whether you may qualify before making a full application. MoneyHelper notes that eligibility calculators can help consumers compare products without affecting their credit file in the same way as a full application.
How to Compare Consumer Finance Options
Before choosing a product, work through this checklist.
1. Decide How Much You Actually Need
Avoid borrowing more than necessary.
The larger the amount borrowed, the greater the potential cost and repayment commitment.
2. Calculate Your Affordable Monthly Payment
Look at your normal income and essential expenses.
Don’t assume you will always have the same amount of spare money. Consider potential changes to household bills or income.
3. Compare the Total Cost
Check:
- APR
- Interest rate
- Fees
- Monthly payment
- Loan term
- Total amount repayable
4. Check the Conditions
Look for:
- Early repayment rules
- Missed-payment charges
- Promotional-period conditions
- Credit limits
- Restrictions
- End-of-agreement payments
5. Check the Provider
For regulated financial services, check the provider’s regulatory status where appropriate.
The FCA explains that most UK financial service providers must be authorised or registered and that authorised firms must meet its standards and rules.
6. Consider Whether You Need to Borrow at All
If you can safely wait and save for a purchase, that may be cheaper than borrowing.
MoneyHelper specifically recommends asking whether you could wait until you have enough money before taking on credit.
The Risks of Consumer Finance
Consumer finance can provide useful flexibility, but borrowing creates financial obligations.
Important risks include:
Interest Costs
The longer you carry a balance, the more interest you may pay.
Missed Payments
Missing payments can result in charges and may negatively affect your credit history.
Over-Borrowing
Having access to credit does not mean you can comfortably afford to use it.
Persistent Debt
Regularly using credit to cover everyday expenses can create a cycle that becomes difficult to break.
Promotional Rates Ending
A product that initially appears inexpensive may become more expensive after an introductory period.
Multiple Credit Commitments
Several small monthly payments can collectively become a significant burden.
Before borrowing, look at your entire financial position, not just whether you can make the next payment.
What to Do If You Struggle With Repayments
If you think you may miss a payment, don’t simply ignore the problem.
Contact the lender as soon as possible and explain your situation.
Depending on your circumstances, you may be able to discuss support options.
You can also seek free debt guidance. MoneyHelper recommends getting debt advice if you are struggling financially rather than relying on further borrowing to cover bills.
Avoid taking out expensive new credit simply to make payments on existing debts unless you have carefully considered the consequences and obtained appropriate guidance.
How Consumer Finance Is Regulated in the UK
The Financial Conduct Authority (FCA) plays an important role in regulating consumer credit and financial services in the UK.
Its rules cover areas such as:
- Responsible lending
- Affordability
- Financial promotions
- Consumer information
- Treatment of customers
- Support for customers experiencing financial difficulty
The FCA has also been reviewing consumer-credit financial promotion rules, including how firms communicate APR and other credit costs to help consumers understand borrowing decisions.
Consumers can use the FCA’s information and firm-checking resources when researching financial providers.
What Is Happening With Consumer Finance in the UK?
Consumer borrowing remains an important part of household finances.
The Bank of England reported that net consumer-credit borrowing by individuals increased to £2.0 billion in July 2026, compared with £1.9 billion in June. Credit-card borrowing accounted for £0.9 billion, while other consumer credit — including areas such as car dealership finance and personal loans — accounted for £1.1 billion.
The same data showed annual growth in total consumer credit of 9.2% in July 2026.
These figures demonstrate why understanding borrowing costs and affordability matters. They do not, however, mean that borrowing is appropriate for every household.
Frequently Asked Questions About Consumer Finance
What is consumer finance?
Consumer finance is a broad term for financial products and services designed for individuals. It commonly includes forms of consumer borrowing such as credit cards, personal loans, overdrafts, vehicle finance and retail finance.
What is the most common type of consumer finance?
There is no single product that is best or most suitable for everyone. Credit cards, personal loans, overdrafts and vehicle finance serve different purposes and have different costs.
Is consumer finance the same as consumer credit?
Not exactly. Consumer credit specifically refers to credit and borrowing arrangements for consumers, while consumer finance is a broader term that can encompass consumer credit and other consumer-focused financial services.
Is consumer finance safe?
It can be, provided you understand the product, can afford the repayments and use an appropriately regulated provider where applicable. The main risks come from unaffordable borrowing, high costs, missed payments and accumulating debt.
Does consumer finance affect your credit score?
Some forms of borrowing and credit applications can affect information on your credit report and may influence future lending decisions. The exact effect depends on the product, your repayment history and other factors.
Should I choose the lowest monthly payment?
Not necessarily. A lower monthly payment may result from a longer repayment period, which can increase the total amount you repay. Always compare the overall cost.
What should I check before applying for credit?
Check the amount you need, affordability, APR or interest rate, total repayment, fees, repayment period, eligibility criteria and important terms and conditions.
What if I cannot afford my repayments?
Contact your lender as soon as possible and consider getting free debt guidance. Avoid assuming that taking out more expensive borrowing is the best way to solve an existing debt problem.
Conclusion
Consumer finance can make it easier to manage major purchases, unexpected expenses and short-term cash needs, but borrowing should always be approached carefully.
The right choice depends on your circumstances. Before applying, work out what you can realistically afford, compare the total cost rather than just the monthly payment, understand the repayment conditions and check the provider where appropriate.
Credit cards, personal loans, overdrafts, car finance and BNPL are not interchangeable. Each has different costs, risks and uses.
If borrowing would leave you struggling to cover essential expenses, consider getting free financial or debt guidance before taking on another commitment.
The best consumer finance decision is not necessarily the one that gives you the most money. It is the one that meets your need without creating an unaffordable financial burden.